
China’s automotive industry is entering a decisive new phase—one defined not by domestic dominance alone, but by a rapidly expanding global footprint. As cooling demand for petrol vehicles and moderating electric vehicle growth reshape the domestic market, Chinese automakers are increasingly turning outward, positioning exports as a critical lever for sustained growth, profitability, and industrial continuity.
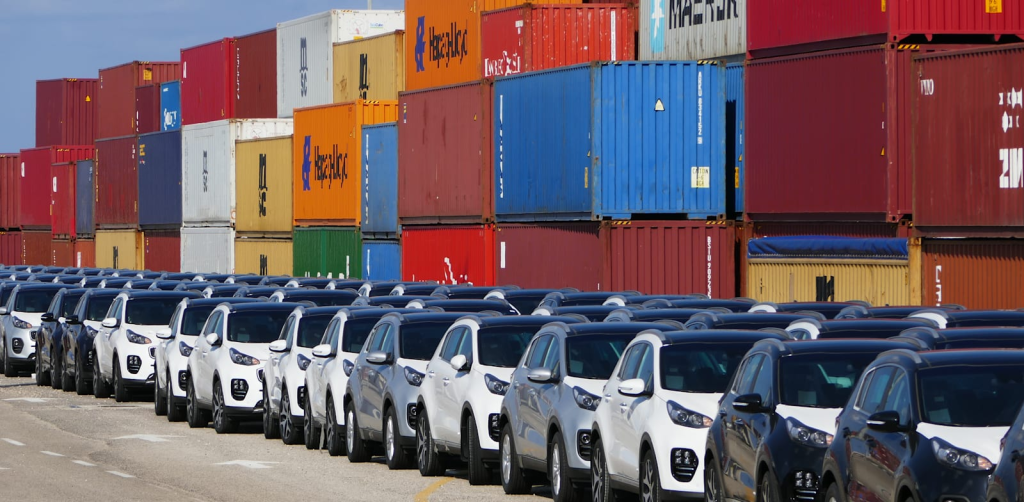
Industry analysts and trade associations project that China’s auto exports will rise by as much as 25 percent this year, surpassing 7 million vehicles, a historic high that underscores the scale of the strategic shift now underway. This export momentum is not simply opportunistic; rather, it reflects a structural recalibration as manufacturers adapt to slowing domestic consumption and intensifying competition at home.
Notably, both internal combustion engine (ICE) vehicles and electric vehicles are contributing to this surge. According to forecasts from UBS auto analysts, ICE exports are expected to climb approximately 4 percent to 3.4 million units, while electric vehicle shipments are projected to soar more than 50 percent to 3.7 million units. Together, these gains signal a dual-track strategy—one that monetizes existing manufacturing capacity while accelerating leadership in next-generation mobility.
Looking further ahead, UBS anticipates Chinese auto exports could reach 9.4 million vehicles by 2030, effectively doubling volumes recorded in 2024. Such growth would firmly entrench China as one of the world’s most influential automotive exporters, reshaping competitive dynamics across Europe, Latin America, the Middle East, and emerging markets.

Exports Become the Industry’s Strategic Pressure Valve
As domestic demand cools, overseas markets have emerged as a vital release mechanism for excess production. Analysts emphasize that exports now function as a stabilizing force, enabling manufacturers to keep factories operating while avoiding disruptive shutdowns.
Rather than retreating, both Chinese and foreign automakers with production bases in China—including established global brands—are actively repurposing domestic plants to serve international demand. This transition is placing mounting pressure on manufacturers outside China, many of whom face higher production costs and slower scaling capabilities.
The China Passenger Car Association (CPCA) has reinforced this outlook, forecasting a 20 percent rise in auto exports, driven in large part by robust electric vehicle demand from leading domestic brands. According to CPCA leadership, the industry is bracing for heightened growth pressure in 2026, making export diversification not just attractive, but essential.
BYD and Industry Leaders Expand Global Footprints
Among China’s automotive giants, BYD has emerged as the most aggressive global expansionist. UBS analysts highlight the company’s plans to double its European retail presence from roughly 1,000 to 2,000 stores by the end of 2026, a move designed to strengthen brand recognition and capture downstream value in high-margin markets.
In total, seven of China’s largest auto groups—BYD, Geely, SAIC, Chery, Great Wall Motor, Changan, and GAC—now operate 31 factories overseas, reinforcing a strategy aimed at mitigating trade barriers, navigating tariff regimes, and embedding operations closer to end consumers.
Overseas sales, which include both exports and vehicles manufactured abroad by Chinese firms, now account for approximately 20 percent of industry revenue and nearly half of total earnings, according to UBS. This imbalance underscores the growing profitability of international markets compared to increasingly crowded domestic battlegrounds.

Domestic Pressures Intensify as Subsidies Fade
At home, conditions remain challenging. Beijing’s gradual rollback of tax incentives and subsidies for electric vehicles is tightening margins across a sector already defined by aggressive pricing and regulatory scrutiny. With more than 100 EV manufacturers competing, profitability has become elusive.
Goldman Sachs analysts warn that earnings will face further pressure this year as competition intensifies, citing the launch of 119 new EV models—nearly one every three days—amid slowing volume growth. Regulatory efforts to curb unsustainable discounting further complicate the outlook, forcing weaker players to confront consolidation or exit.
Meanwhile, the decline in petrol vehicle demand presents an existential challenge for companies lacking competitive EV offerings. Once the backbone of China’s automotive boom, ICE sales have fallen sharply—from a peak of 23.9 million units in 2017 to an estimated 14.5 million in 2025. UBS forecasts suggest ICE sales could plunge below 5 million units by 2030, marking the lowest level in roughly 25 years.
The Race to Scale Technology and Affordability
As the industry pivots, experts emphasize that long-term success will hinge not solely on export volume, but on technological leadership. According to veteran industry advisers, the defining race centers on scaling advanced batteries, software, and electronics while maintaining affordability.
The manufacturers that can democratize cutting-edge technology—delivering differentiated products at scale—will define the next era of global automotive leadership. In this context, China’s export push is not merely a response to domestic slowdown; it is a calculated bet on global relevance, resilience, and industrial supremacy.
As markets absorb this shift, one reality is increasingly clear: China’s automotive story is no longer confined within its borders. It is being written on highways, showrooms, and factory floors around the world.
